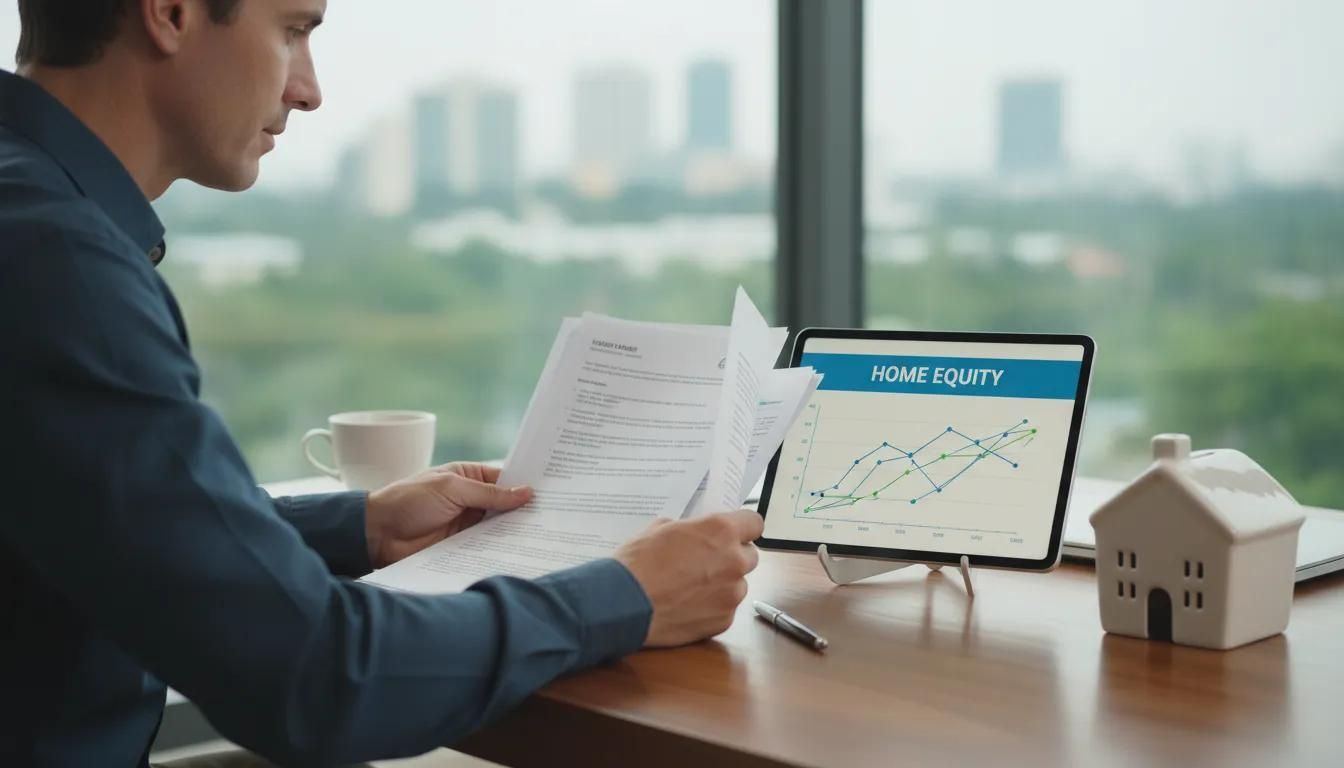
Could your mortgage be your most underused investment tool?
Could your mortgage be your most underused investment tool?
Many homeowners treat a mortgage as a bill to be paid down rather than a tool to be managed — and in doing so, leave real opportunity on the table.
Reviewing and restructuring existing financing can, in the right circumstances, free up monthly cash flow, shorten the path to being mortgage-free, and even fund a first or next investment property.
More often than not, the difference comes down to strategy and timing rather than income.
Why do so many owners underuse their mortgage?
The most common obstacle is not a lack of money — it is a lack of a plan. A mortgage is typically treated as a fixed obligation to be chipped away at over twenty-five or thirty years, when in practice it is one of the most flexible financial tools most households will ever hold. The LIVEHERE team has noted that the deeper they get into the financing side of real estate, the more they encounter the same pattern: capable, well-positioned owners who simply were never shown how their mortgage could work harder for them.
That gap matters because small structural changes can compound. The way existing debt is arranged, refinanced, or layered against the equity a homeowner has already built often determines whether a second property, a renovation, or an earlier retirement is realistic — long before income becomes the limiting factor.
What does restructuring actually look like?
Consider a recent example. A client approached LIVEHERE about buying an investment property but was struggling to make the numbers work while also planning for retirement — a tension many would-be investors recognize. Rather than starting with the new purchase, the conversation started with what the client already owned. A review of his existing properties and financing revealed a path to becoming mortgage-free in roughly two years, restructuring his current arrangements so that acquiring an additional investment property would carry effectively no net cost — while improving his monthly cash flow by around $2,000.
It is worth stressing that this is one household's situation, not a formula. Outcomes depend entirely on individual circumstances — equity, existing rates, income, and goals — and none of this constitutes personalized financial advice. The broader point is simply that the starting question is often not "can I afford another property?" but "is my current financing structured as well as it could be?"
Why does financing expertise matter when deals get complicated?
Real estate rarely moves in a straight line, and the value of financing know-how tends to show up precisely when something goes wrong. In one recent closing, a lender requested a Notice of Assessment roughly a week before the deal was due to complete, only to run into a complication on the Canada Revenue Agency side — the kind of last-minute snag that can derail a purchase entirely. Having the relationships and tools to resolve it quickly is what kept the deal on track.
The same principle extends well beyond the paperwork. Owning property means contending with the unglamorous realities — a summer storm that sends a house full of interconnected smoke detectors into alarm, a pond system that needs an expert on-site over the weekend, permitting issues that have to be worked through. A team built to solve those problems as they arise is as much a part of the value as the transaction itself.
What about investors and the student-rental market?
Seasonally, the fall brings its own rhythm. The student move-in around the University of Guelph has wrapped up, and attention is already shifting to next year — parents are beginning the search for housing for their children well ahead of the coming cycle. On the investment side, conversations about structuring and financing continue to pick up as owners look to position themselves for the busier months ahead. For anyone considering a student rental or a first investment property, the planning window is open now, not in the spring.
What comes next?
As the market moves into a more active fall season, the owners and investors who get ahead tend to be the ones who treat financing as a strategy rather than an afterthought. Whether the goal is an earlier mortgage payoff, stronger monthly cash flow, or a first step into investment property, the sensible first move is to understand how the pieces already in place could be working together more effectively.
For those weighing a move or simply wondering whether their current setup is as efficient as it could be, it is a good time to start the conversation.